How can I protect my savings from tax?
There are 2 key ways to protect your savings from tax; the PSA (Personal Savings Allowance) and an ISA (Individual Savings Account). Find out more about how you can maximise your tax-free savings below.
What is the Personal Savings Allowance (PSA)?
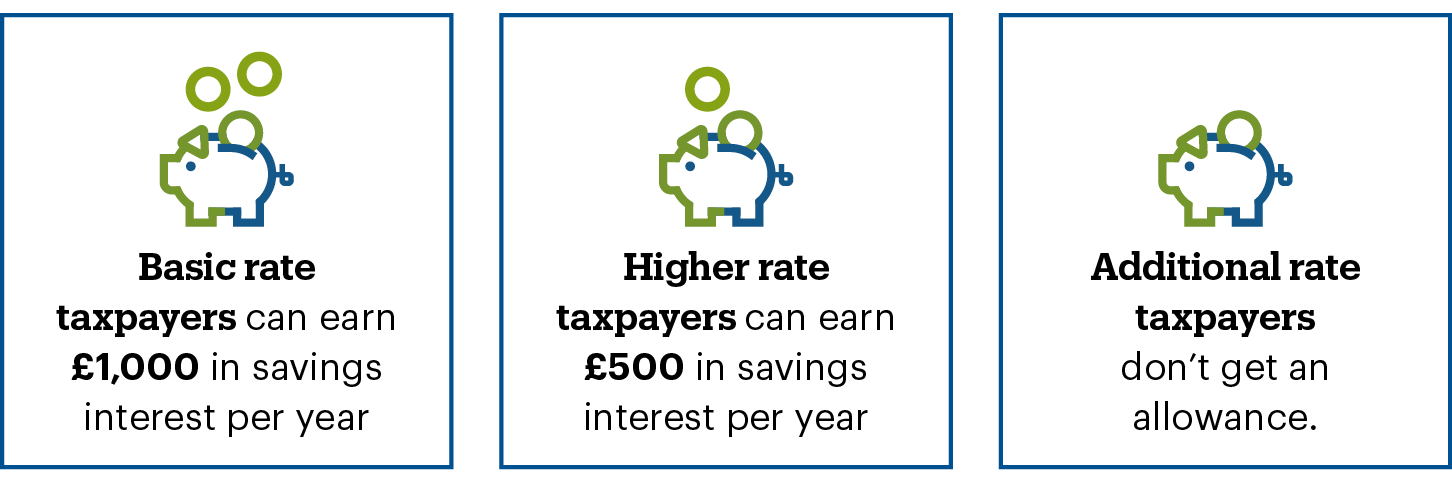
The PSA is a tax-free allowance which lets you earn interest on your savings each year, up to a threshold, without paying tax on the interest earned, depending on the rate of income tax you pay.
If you earn less than £17,570 per tax year, you may be able to earn more savings interest without paying tax. Please see to the Gov.uk website for more information.
HM REVENUE AND CUSTOMS PRACTICE AND THE LAW RELATING TO TAXATION ARE COMPLEX AND SUBJECT TO INDIVIDUAL CIRCUMSTANCES AND CHANGES WHICH CANNOT BE FORESEEN.
What is an ISA?
ISA stands for Individual Savings Account and is a tax-free way of saving. Currently you can deposit up to £20,000 into ISAs each tax year, which runs from 6th April to 5th April each year, and you’ll pay no tax on the interest you earn.
If you’re interested in opening an ISA, you can view our existing range here.
Can I use the Personal Savings Allowance and my ISA allowance?
Yes, you can make use of both allowances and this guide can help you make the most of each.
How much do I need to save before I reach my PSA limit?
The charts below show how much you would need to save at interest rates between 1% and 5% to reach your PSA limit.
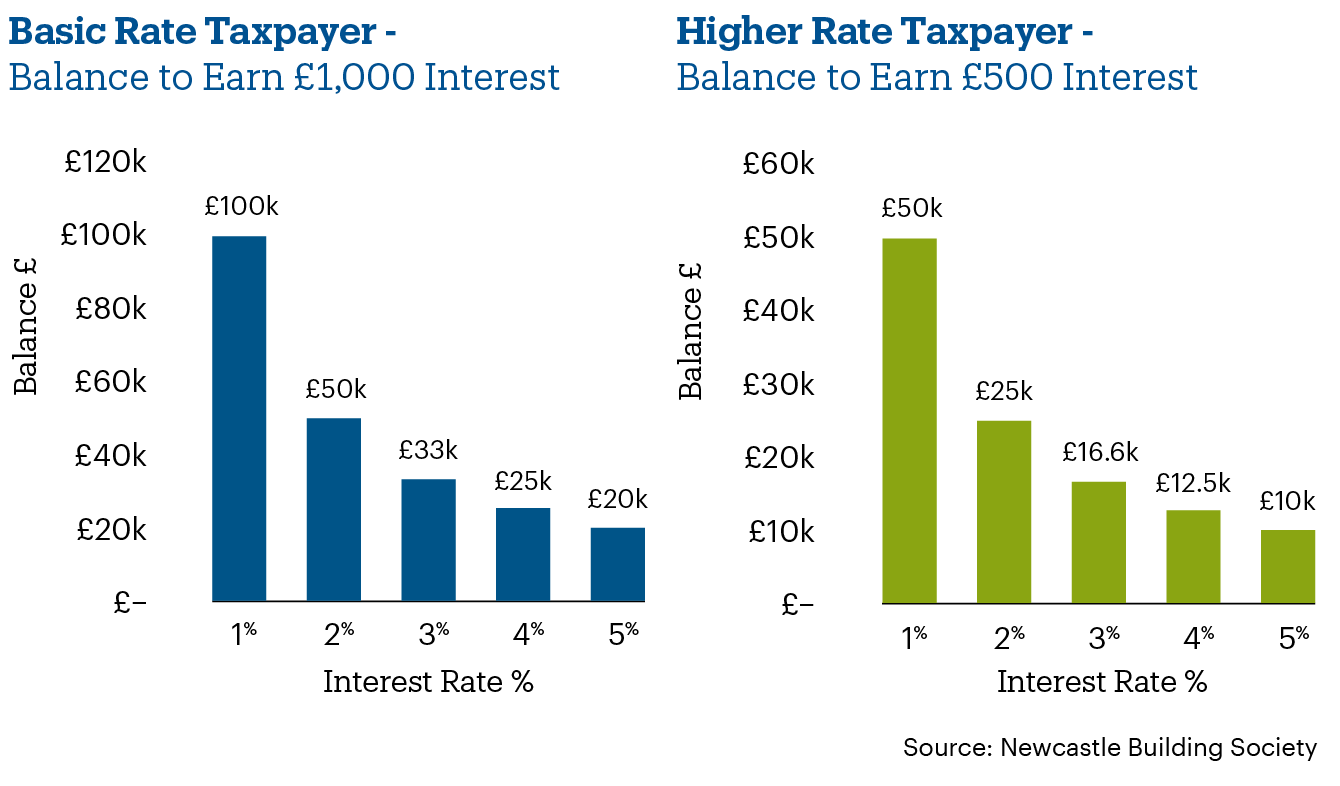
Please note if you invest in a non-ISA fixed term savings account with a term longer than 1 year, any interest that is paid into the account will count towards your PSA in the tax year when the funds become accessible, i.e. upon maturity.
What are the benefits of an ISA?
- Money in an ISA will always be protected from tax, year after year, for as long as the money stays in an ISA.
- Your ISA allowance renews each new tax year – so you can build up a bigger tax-free pot over time.
- You will always be able to access your ISA funds, however, some ISAs may carry a penalty for this.
- The value of your ISAs can be transferred to your spouse or civil partner if you pass away, protecting your tax-free savings.
- ISA interest does not count toward your Personal Savings Allowance, meaning you can use your full ISA limit and still keep your entire £500 or £1,000 PSA for regular savings.